China’s iron ore buying clout makes each deal a market event
State-backed iron ore buyer CMRG has had a good year, securing deals with two of its biggest suppliers that establish its dominance of a market worth north of $100 billion.
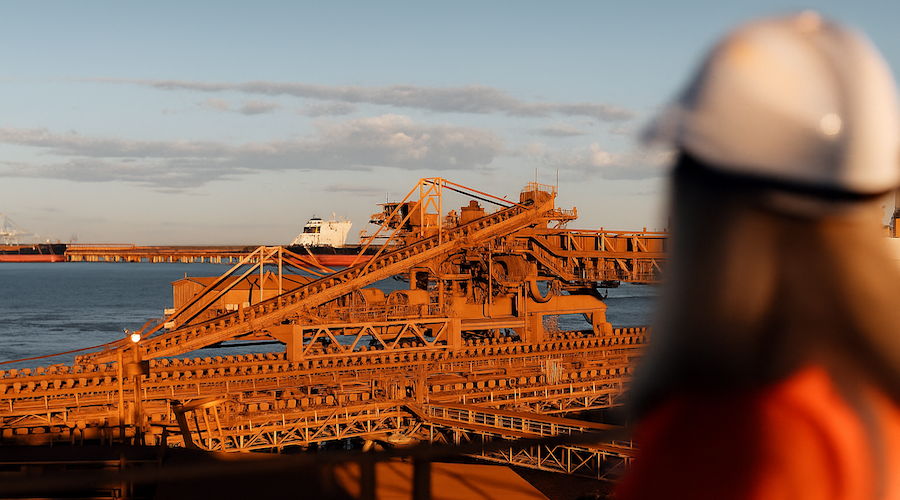
BHP is China’s third-biggest iron ore supplier. (Image courtesy of BHP.)
State-backed iron ore buyer China Mineral Resources Group (CMRG) has had a good year, securing deals with two of its biggest suppliers that establish its dominance of a market worth north of $100 billion.
But success could present new challenges. The agreements struck with Australian mining giants BHP Group and Rio Tinto Group aren’t permanent. BHP’s will need resetting as early as next year. Smaller rival Fortescue Ltd. is still wrangling over terms. The negotiations themselves could now become a recurring price risk.
Introducing centralized iron ore purchasing for China’s sprawling steel industry minimizes the number of negotiations, but each one becomes much more important. Bargaining over pricing and which benchmarks to use, contract durations and settlement currency, are now confined to a single track of high-stakes talks.
“The risk now sits in discrete events: bans, easings and settlements that can move prices within a single session,” said David Cachot, iron ore analyst at Wood Mackenzie Ltd. “CMRG has introduced a greater degree of event-driven risk linked to negotiations, trade restrictions and procurement directives.”
CMRG was set up in 2022 to represent the world’s largest steel industry, which buys more than 70% of the world’s seaborne iron ore, converting it to about 1 billion tons of metal a year. Beijing had long complained about the profitability gap between the big miners and the mills that rely heavily on imported ore, particularly from Australia and Brazil.
Pooling all that purchasing power has given CMRG much greater leverage in talks that were previously conducted between individual miners and steel companies, allowing it to challenge how prices are set and in what currency.
Ultimately, the goal is lower costs for mills. The company has made a big effort to consolidate market data to improve its understanding of supply and demand. Last week, it unveiled artificial intelligence agents to track vessels and capture price differentials and inventory levels at ports.
But the negotiations have been tense, creating uncertainty and volatility in a once predictable market. The months-long standoff with BHP saw unofficial restrictions on its ore that pushed up prices. Fortescue has taken a more combative approach, and with product curbs in place has warned its operations could be affected if talks stretch beyond the end of the year.
Rio Tinto reached its accord with less friction, agreeing on a longer contract that runs through May 2028. Meanwhile, Brazil’s Vale SA has managed to evade term deals for now, sticking with spot contracts due to its different product mix.
A Rio Tinto spokesperson said the company doesn’t comment on details of confidential commercial negotiations, but noted its “long and successful relationship with our customers in China.” BHP and Fortescue declined to comment. CMRG didn’t respond to a request for comment.
If the government extends CMRG’s remit, other commodities markets that depend on China might soon find themselves wrestling with an unfamiliar playbook. Flush from its success in iron ore, the company’s next target could be copper or another metal.
Longer agreements
The dispute with BHP showed that worries over possible disruptions can raise prices — particularly on futures markets that attract speculators — even before actual supply is materially affected. That’s arguably helped keep iron ore prices higher than they should be this year.
It means that both sides may have reason to favor longer agreements.
“Downstream participants value above all the predictability of raw material costs,” said Zhong Hong, a researcher at Citic Futures Co. “Multi-year frameworks support production planning, profit budgeting and long-term volume commitments, and reduce operational volatility stemming from sharp spikes and collapses in spot prices.”
And the balance of power could shift quickly between talks. CMRG has negotiated over the past year against a backdrop of weak Chinese steel demand, pressure on mill margins and new supply from Guinea’s Simandou project. In later rounds, those conditions might have changed.
“Pricing power is less permanent than it looks,” said Sushmita Vazirani, lead iron ore analyst at Kpler. “If the market tightens again, through supply disruptions or a demand recovery, leverage would swing back toward the miners.”
“The structure has changed but the balance of power is still cyclical,” she said.
(By Katharine Gemmell)
Comments
No comments yet.